The zone word this week is Value — the durable reading, standing since late July, four Mondays running. The durable word requires a new zone to hold before it replaces the standing one. The raw weekly reading has moved to Neutral; the rule is that it must hold to govern. Whatever next Monday reads, the word follows the rule, not the week’s mood.
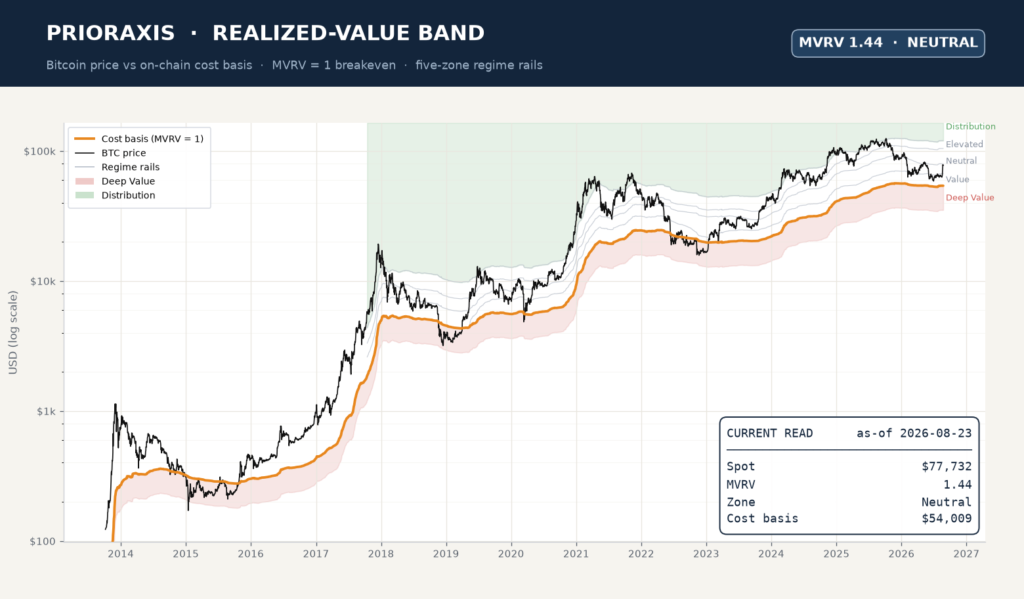
Price stands at 1.44 times what the market as a whole paid for its coins. Read that ratio carefully: its denominator — the realized value — is held at 10 August under a ruled data hold, so part of the rise in the ratio is the hold, not the market. What can be said honestly: the market is no longer measurably cheap. How far from cheap is not yet measurable, and this page says so rather than guessing.
The composite enters the week at 0.3704, up from 0.1623 — nineteen times the largest move previously in this record. One input did it: price rose 21.4 percent, crossing from just below the 200-week average to a fifth above it. Confirmed deep value — the reading this series had carried since June — ended in five trading days. The structure of the move is worth recording. In the twenty-four hours read on August 20, $1.45 billion of leveraged positions were forcibly closed — 97 percent of them bets against the price, at six times the prior week’s daily average — while the momentum of open interest fell through the advance. Positions being closed during a rally is what forced covering looks like from the other side. Sentiment crossed from fear on Monday to greed by Thursday, and there it has stayed. The market re-priced faster than it re-shaped. The early lifting was forced covering — that is what the liquidation and open-interest record shows. At the same time, demand arrived through the fund channel: $1.9 billion net into the spot ETFs across five green sessions in the closed week, the largest such window in this record, while the US spot premium stayed negative. Force started the move. What sustains it is not yet decided, and slot six says why.
Nothing was bought last week. The week’s sizing never ran, and on August 20 — with price already 9.5 percent above the week’s close of record — the week was closed unsized by a dated decision rather than a late chase. A week in which nothing fills is a complete record; the close and its reasons are in the dated record, and from this week forward, weeks live on a ledger.
Confirmation. The composite is a number; the zone word is a commitment, and between them stand two different rules. The engine confirms a deep-value reading when the score is deep enough to speak alone — or, in the shallower part of the band, when the market corroborates it: price still near the long average, components at their floor. This week neither held. Price left the average behind and the components left the floor, and with them went the confirmation — while the composite itself, at 0.3704, still sits inside the deep-value band. That is why this page can say both things at once. And the public word obeys its own second rule — the durable rule, two consecutive Mondays — which is why one violent week can move a number nineteen times the largest step in this record, and cannot, by rule, move the word.
Two things. Whether demand or unwinding dominates from here. The fund channel ran strongly positive in the closed week; the US spot premium did not corroborate it; and the flows that settle that disagreement settle over weeks, not days. And the true current cost basis of the market: the realized-value series is held at 10 August, so how much of the week’s move the holders themselves ratified is not yet visible. When the hold lifts, this page reports what it shows.